Car finance mis-selling claim pack: PCP & HP complaint templates
Check if you're owed money, write your own complaint and track it through the FCA redress scheme without paying a claims firm
- Download it the moment you've paid
- Print at home, or use it on your phone or tablet
- Secure checkout by Stripe
Why it helps
A practical, plain-English pack for anyone who financed a car on PCP or HP between 2007 and 2024 and wants to check for mis-sold commission without paying a claims company. Includes an eligibility checklist, ready-to-send complaint and Ombudsman letter templates, and a claim tracker to keep everything on schedule through the FCA's redress scheme.
What's inside
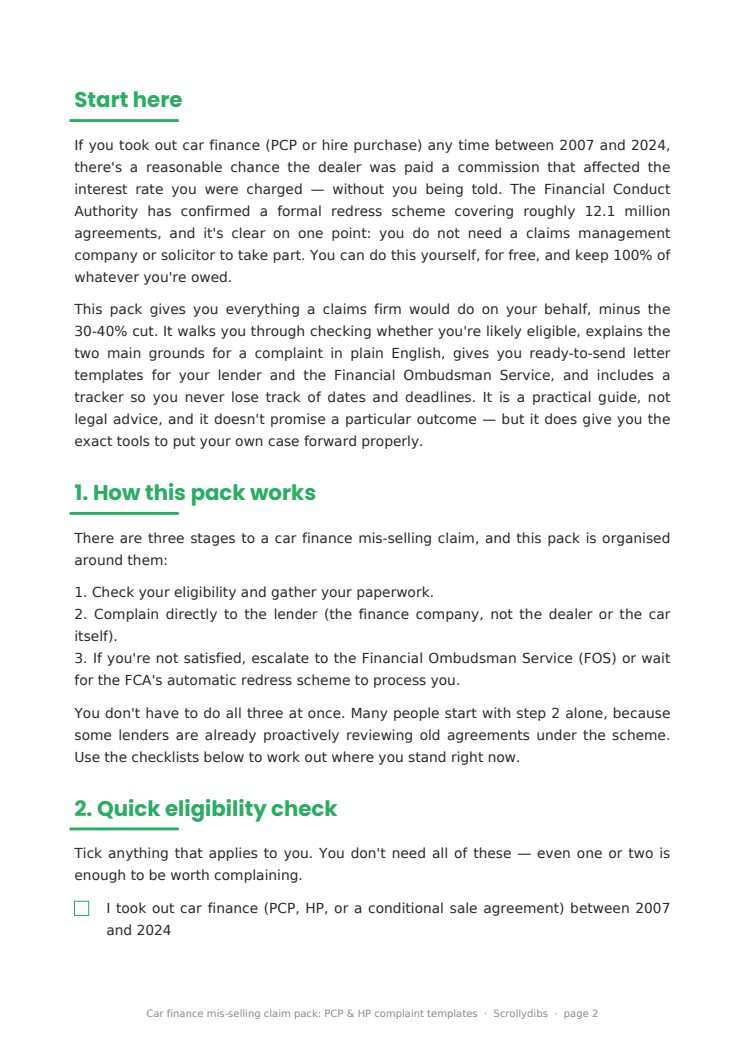
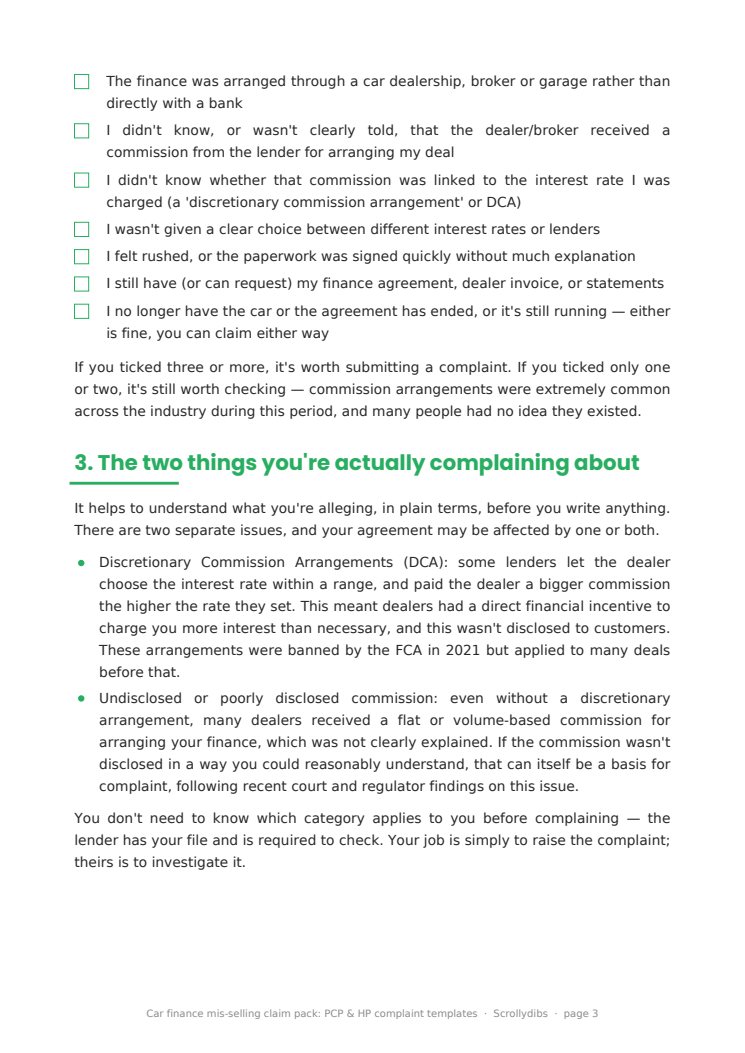
- Eligibility checklist to see if your PCP or HP agreement is worth complaining about
- Plain-English explanation of discretionary commission arrangements and undisclosed commission
- Ready-to-send complaint letter template for your lender
- Follow-up/chase letter if you don't hear back in time
- Financial Ombudsman Service referral letter template
- Claim tracking log to record dates, references and offers
- Guidance on reviewing a redress offer before accepting it
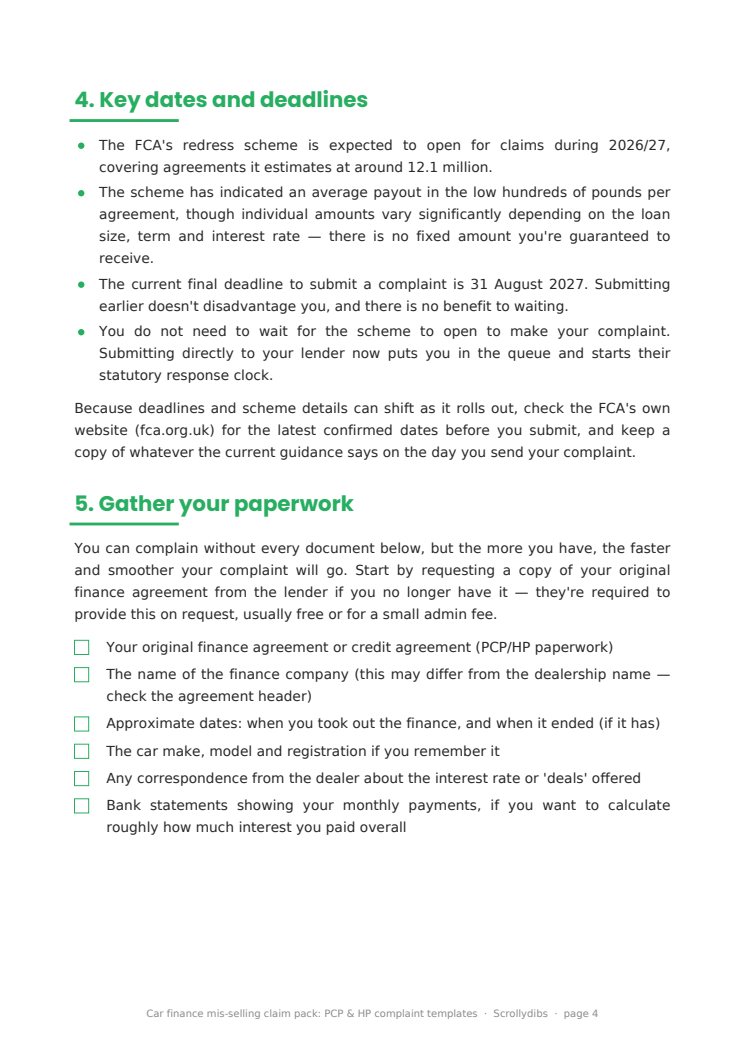
- Key deadlines and what to check before you submit
Take a look inside
Questions
Do I definitely get money back if I complain?
No — this pack helps you put forward a proper complaint, but whether you're owed anything, and how much, depends on your specific agreement and the lender's findings. Not every agreement involved an undisclosed commission.
Is this legal advice?
No. This is a practical, plain-English guide to the complaints process based on publicly available FCA and Financial Ombudsman Service information. For advice specific to your situation, you can contact the Financial Ombudsman Service or Citizens Advice, both of which are free.
Do I need to pay anything to make a claim?
No. Complaining to your lender and referring to the Financial Ombudsman Service are both free. You never need to pay a claims management company to access either process.
What if my agreement was before 2007 or after 2024?
The main focus of the current redress scheme is agreements from 2007 to 2024, but it's still worth checking your paperwork — if you're unsure, contact the lender directly and ask them to check their records.
What if the dealership has closed down?
That doesn't affect your claim. Your complaint goes to the finance company (the regulated lender), not the dealership, so it's still valid even if the dealer no longer trades.
How long will this take?
Lenders typically have 8 weeks to respond, though many are currently taking longer due to the volume of claims tied to the redress scheme. Keeping a tracker (included in this pack) helps you know when to chase or escalate.